13 days into AEP, we’re watching enrollment quality and plan mix closely. The team analyzed over 350k client plans and apps, and here’s what we’re seeing:
1. Cost increases are hiding in the out-of-pocket max. More than 2x as many beneficiaries face a MOOP increase over $500 compared to last year.
2. HMOs are nearly 30% of all apps and SNPs 37%, while PPOs are declining compared to last year, which tracks with a growing carrier focus on HMOs and SNPs.
3. Many beneficiaries may be waiting until after the election to enroll, so agents are working their existing books first, especially clients whose plans have exited.
If you’re running an agency, make sure you’re asking the following:
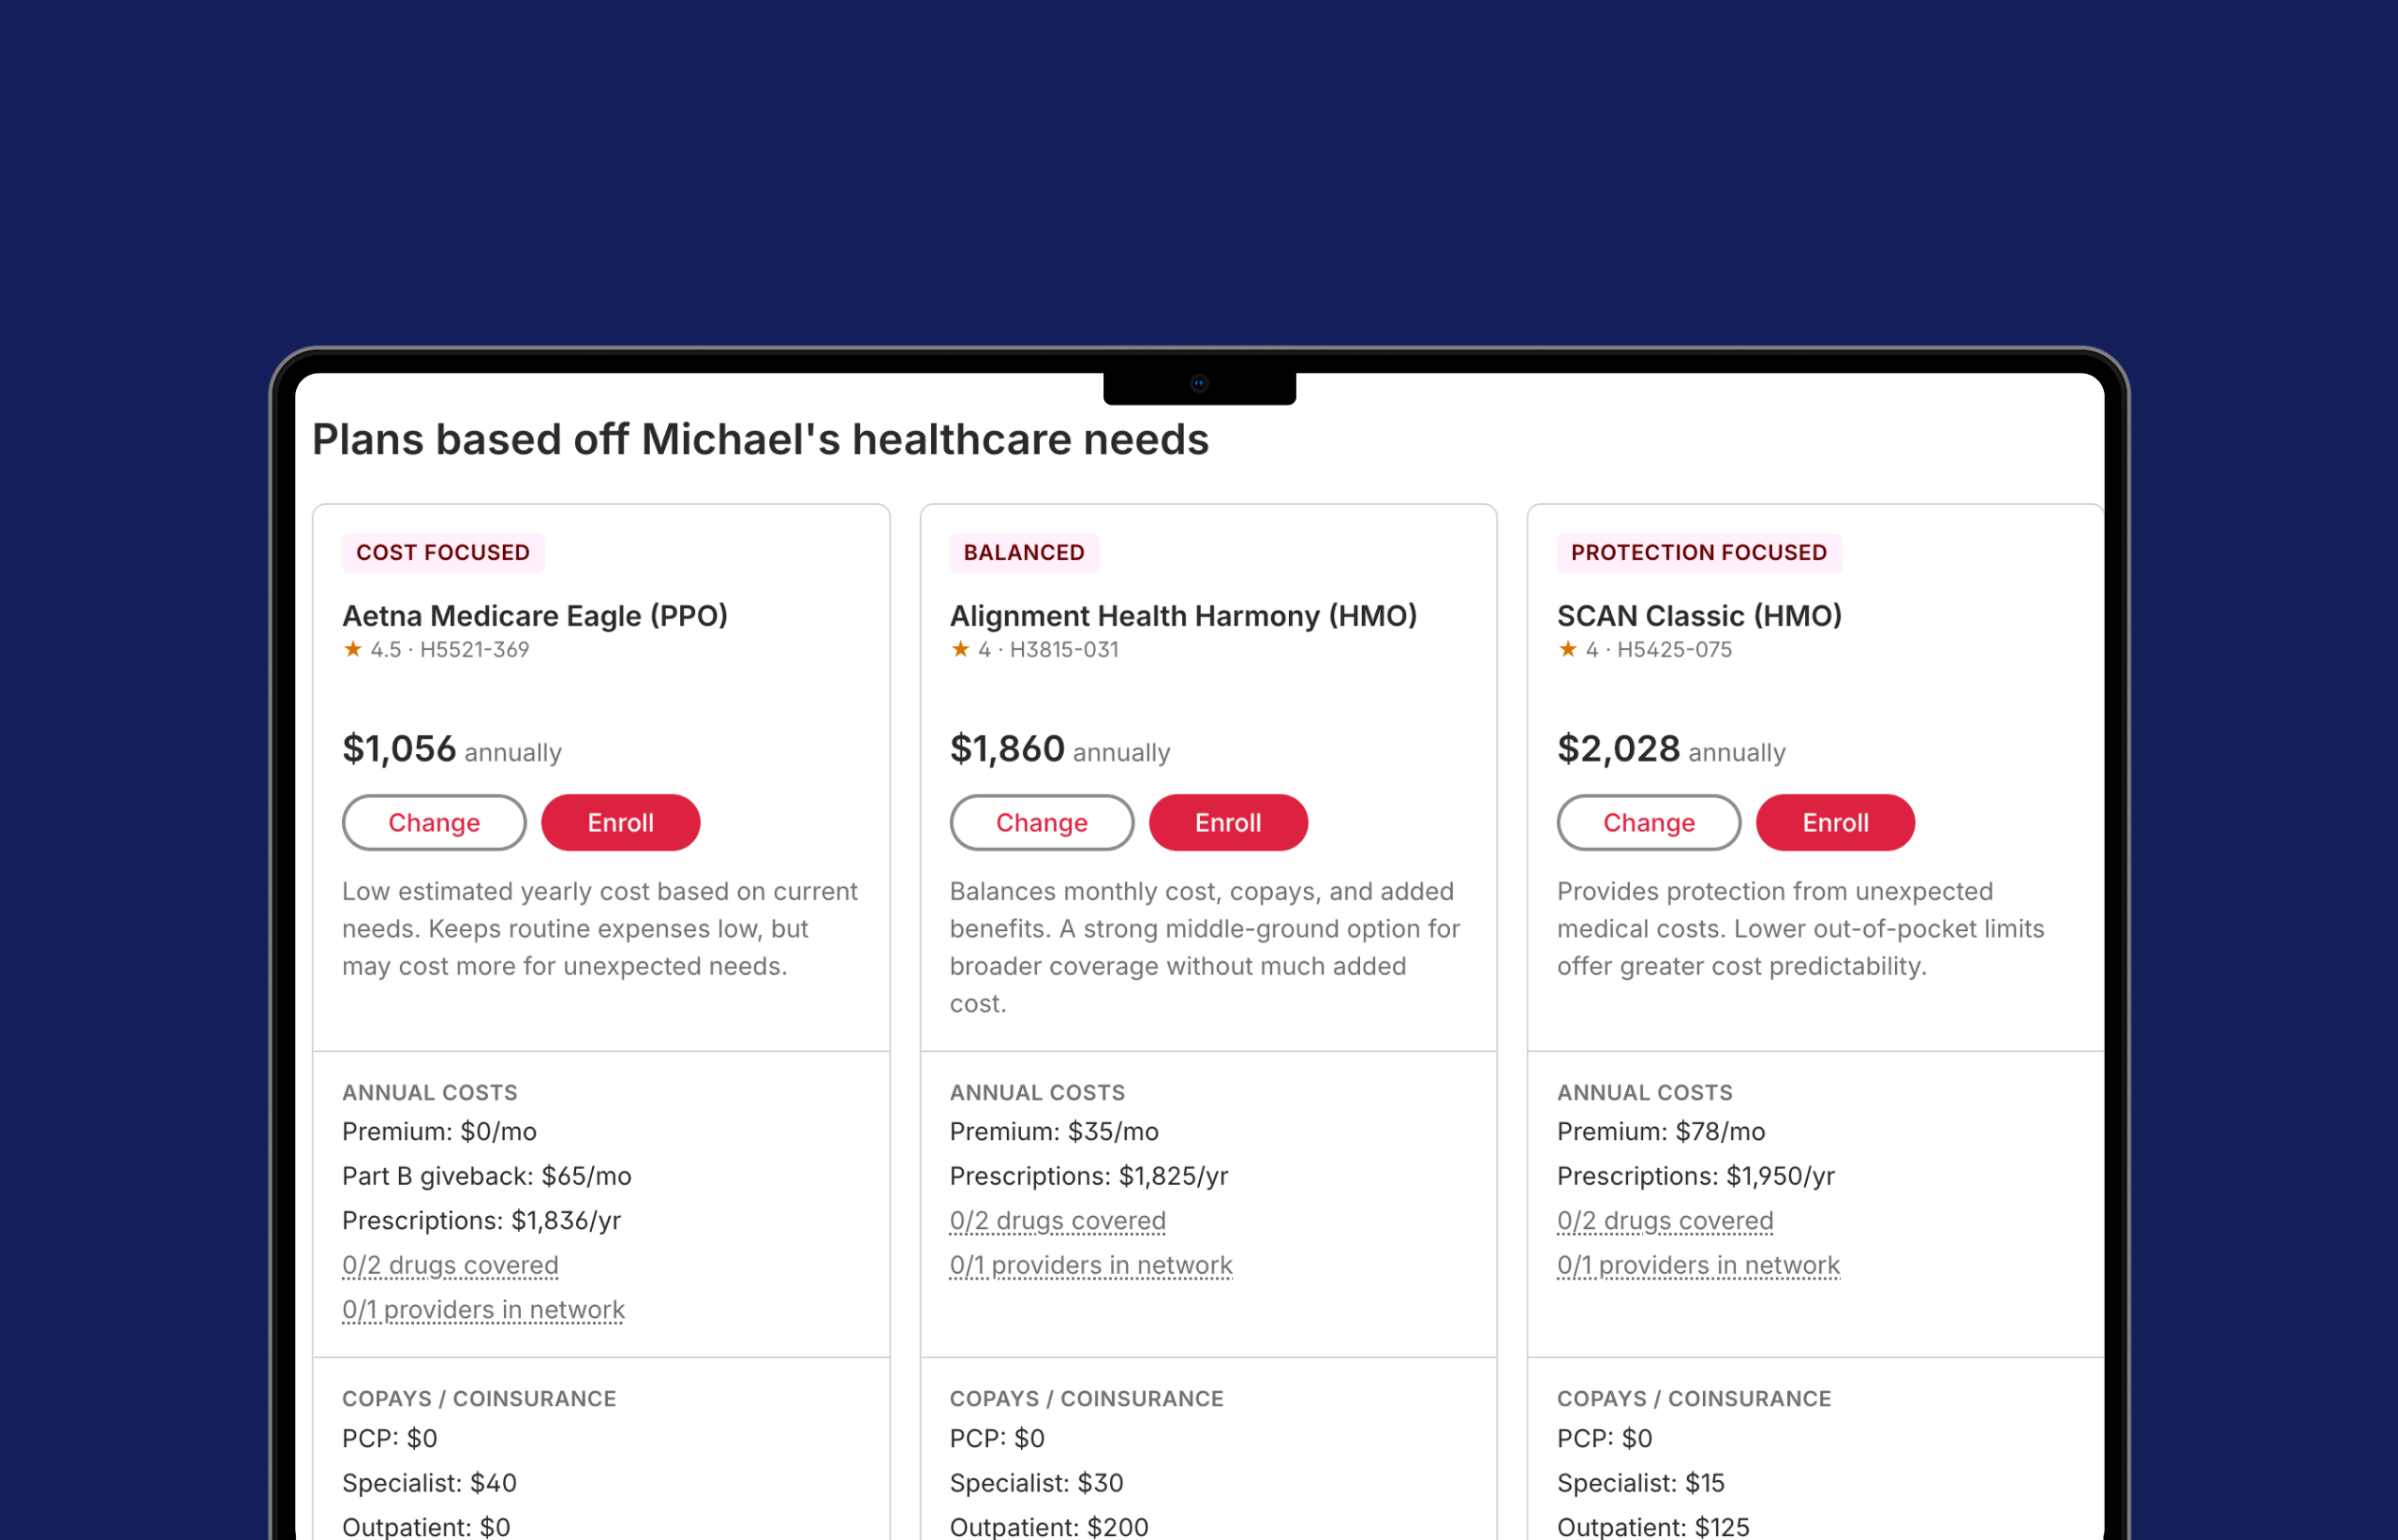
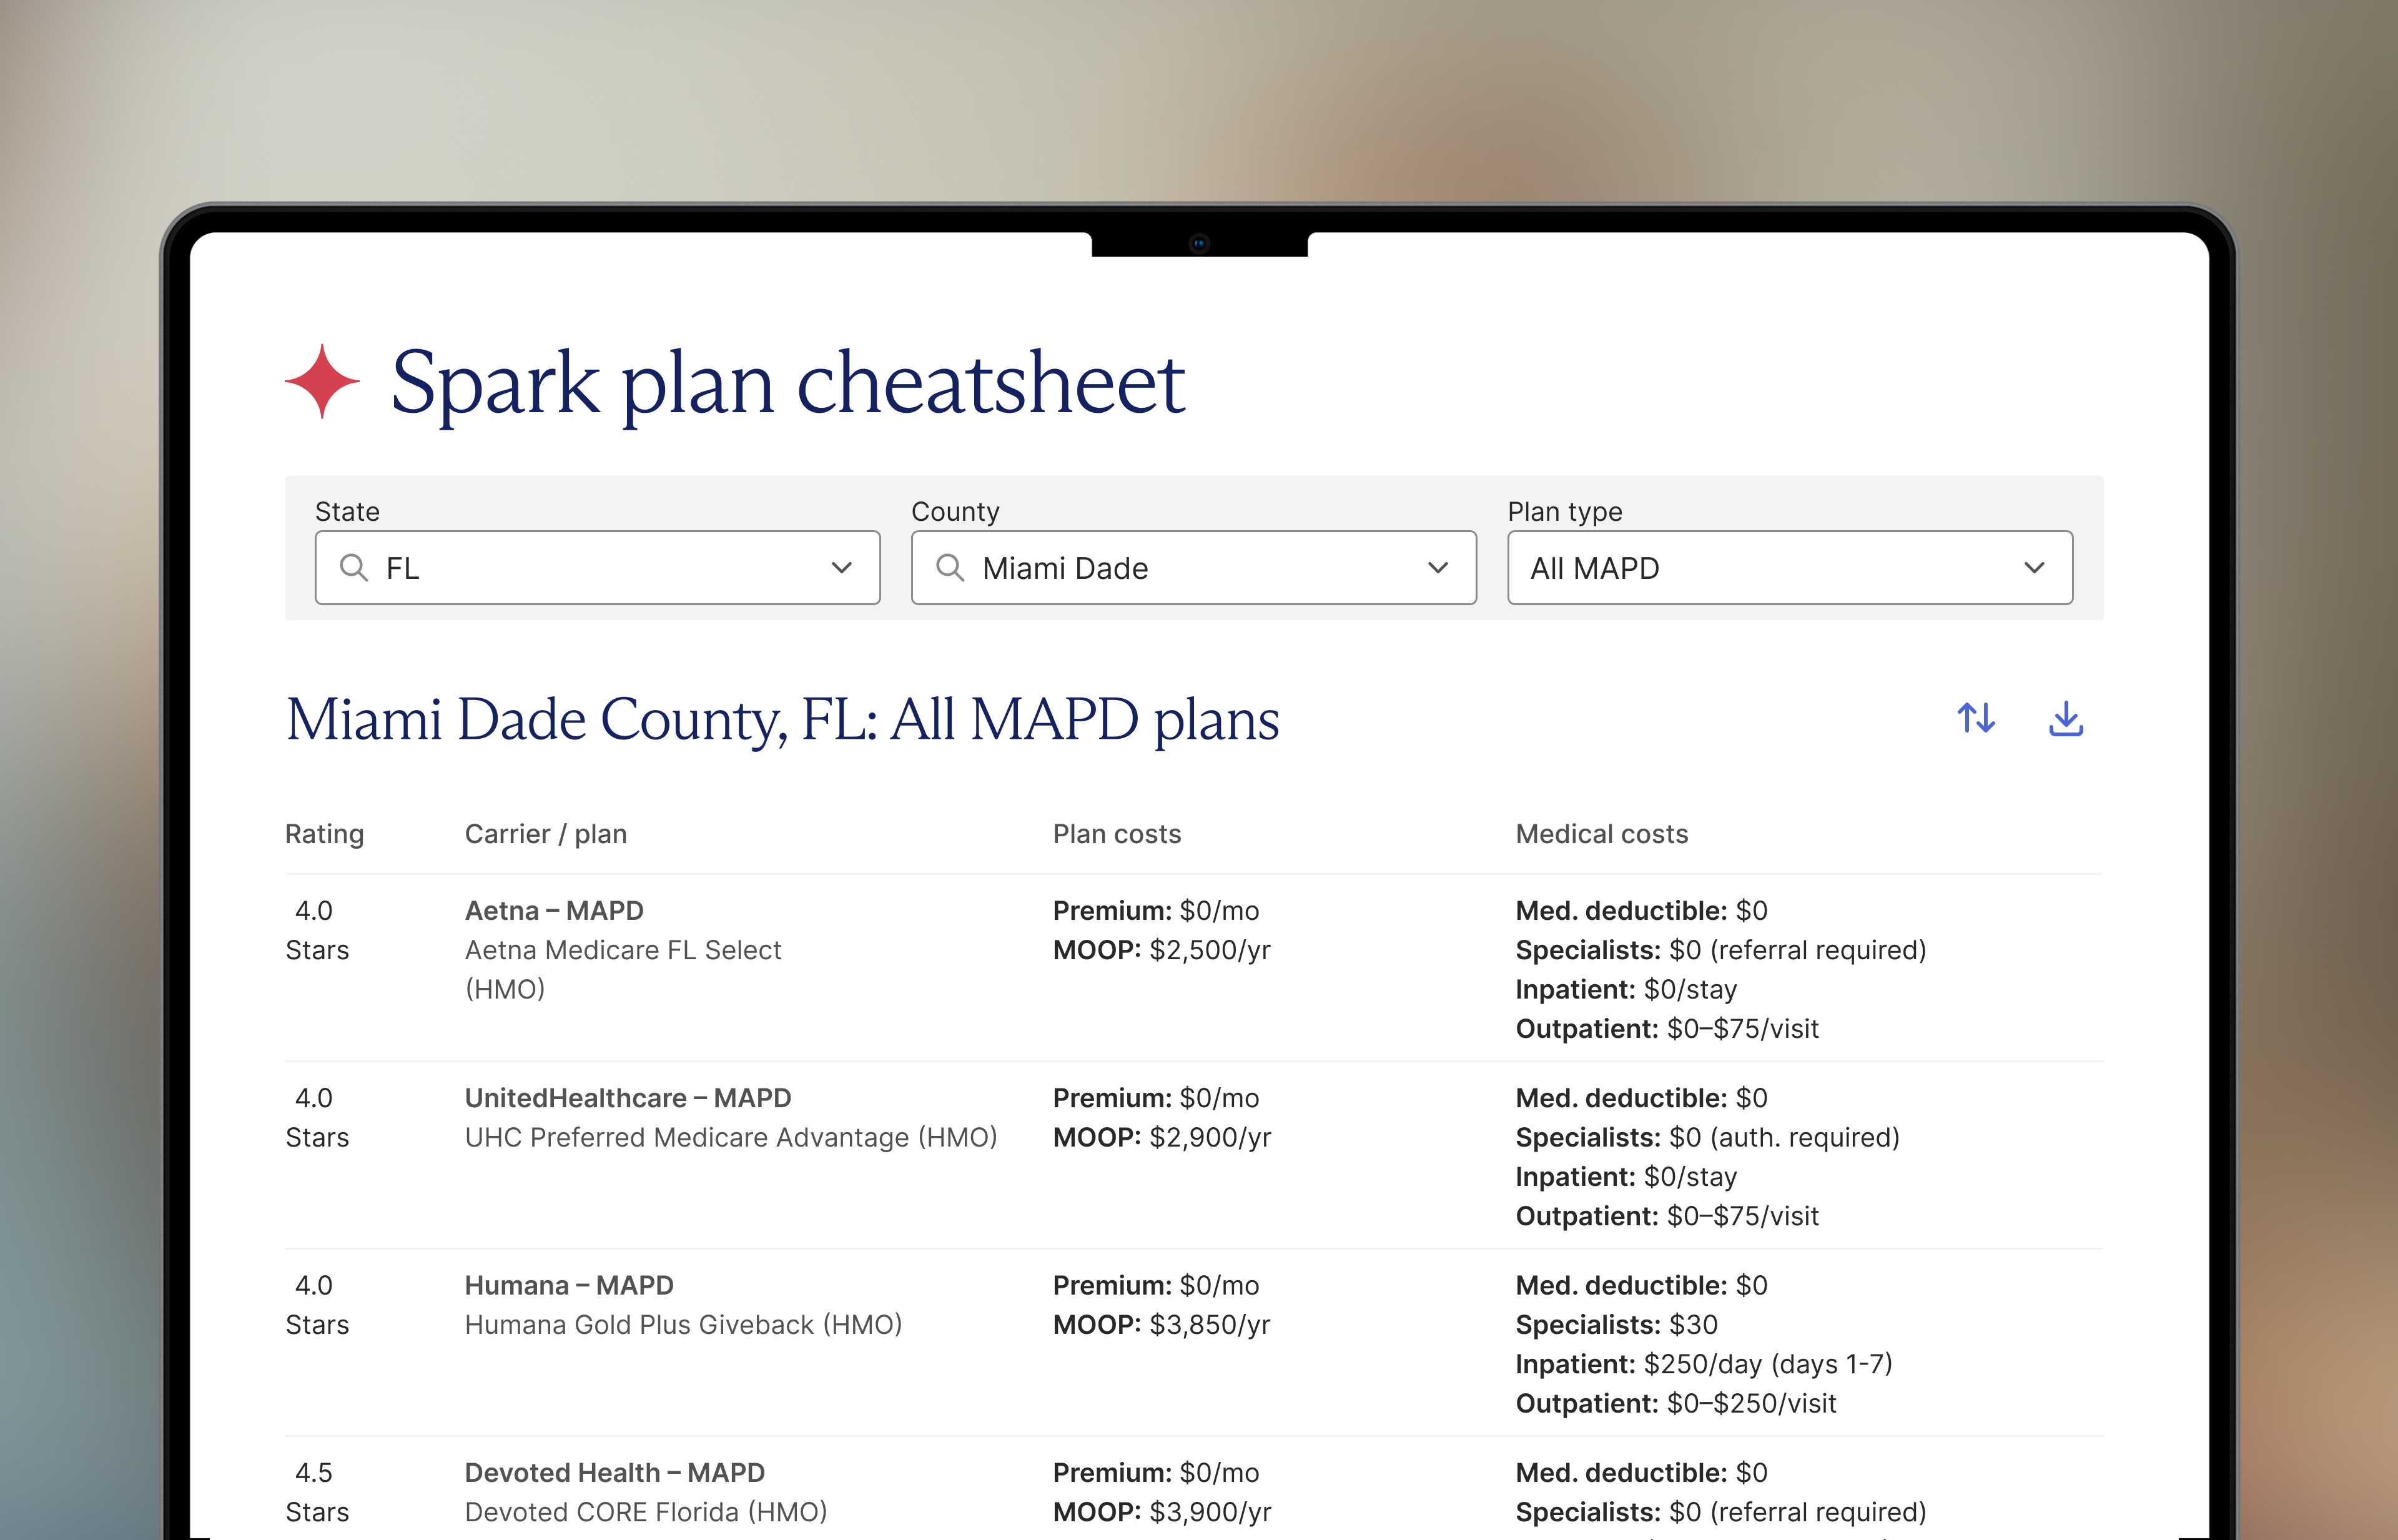
- How well are your agents presenting cost and coverage tradeoffs, especially to price-sensitive clients? The cheapest plan isn’t always the best plan, and agents should do side-by-side comparisons that go beyond the premium (tools like Spark's Plan Fit can help).
- We expect new business to pick up post-election. Do you have the capacity to handle the volume increase?
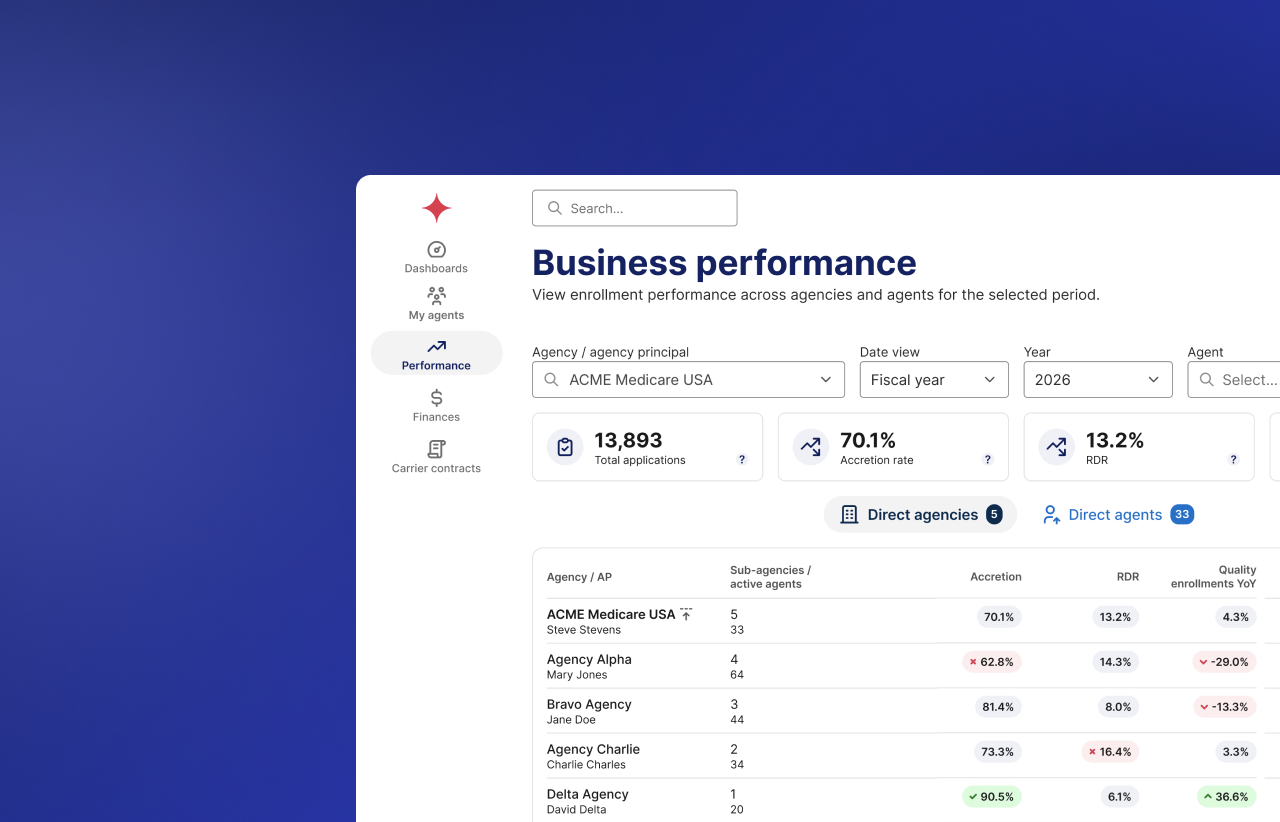
- Are you tracking your RDR, CTM, and HRA completion rates, and who needs coaching? Carriers are closely monitoring quality metrics this year.
Plenty of opportunity remains in the next six weeks!