Diversifying beyond Medicare Advantage isn't just a nice-to-have. It's what protects an agent's income and keeps clients around longer. That's the takeaway from Maximizing LTV Beyond MA, hosted by Jesse Hendon (Head of Ancillary & Life) during our Built for AEP 2027 virtual kickoff.
Here's what was covered, and how to start putting it into practice.
Stop over-indexing on one plan
Jesse opened with a cautionary example: an agent named Mike who built his entire book around a single carrier. When that carrier made changes, Mike's income went with it.
To mitigate risks and ensure income stability, Jesse urged agents to diversify their offerings:
“You don’t wanna be a plan exit away from something happening to your paycheck.”
Diversifying isn't just smart business. It's income insurance.
Bundling: The Secret to Client Retention
Companies like Progressive and State Farm have built loyalty through bundling, and the same logic applies to Medicare agents. Once a client has three products with an agent, they're exponentially more likely to stick around, because there's real friction in leaving.
That means rethinking the job itself: not a Medicare agent, but a retirement benefits advisor, someone selling multiple products to the same consumer instead of one.
The math behind cross-selling
The numbers make the case on their own. Bundling an MA product with a hospital indemnity plan, for example, averages an agent $360 in that first year and a $60.70 renewal after that. Multiply that across a book, and the effect compounds, the same way compound interest builds wealth over time. Compounding commissions are the insurance agent's version of that superpower.
Run the math on retention alone: an agent selling 250 MA clients a year who holds onto that book is looking at an average of $570,000 a year in renewals by year ten. But that only works if you hold onto the book. Churn half your clients every year, and those gains never get the chance to compound.
Products worth adding to your portfolio
A handful of products stand out as easy additions. Here are some key suggestions:
Hospital indemnity plans. A strong bundling foundation, averaging around $300 a day for six days. Riders like cancer coverage and skilled nursing facility benefits help close a real gap: Medicare Advantage covers the first twenty days in a skilled nursing facility, but leaves a co-pay for days twenty-one through one hundred.
Long-term and short-term care. Custodial care is the single biggest gap in Medicare today, full stop. Starting long-term care conversations early, especially with younger clients, means coverage is already in place if something like dementia or Alzheimer's shows up later.
Dental, vision, and hearing. The advice here is simple: assume the client wants this coverage, because they do.
Final expense plans. Life insurance rounds out the picture, covering everything from funeral costs to long-term care needs. Carriers worth exploring include Mutual of Omaha, Aetna Supplemental, and Newbridge.
A four-week plan to get started
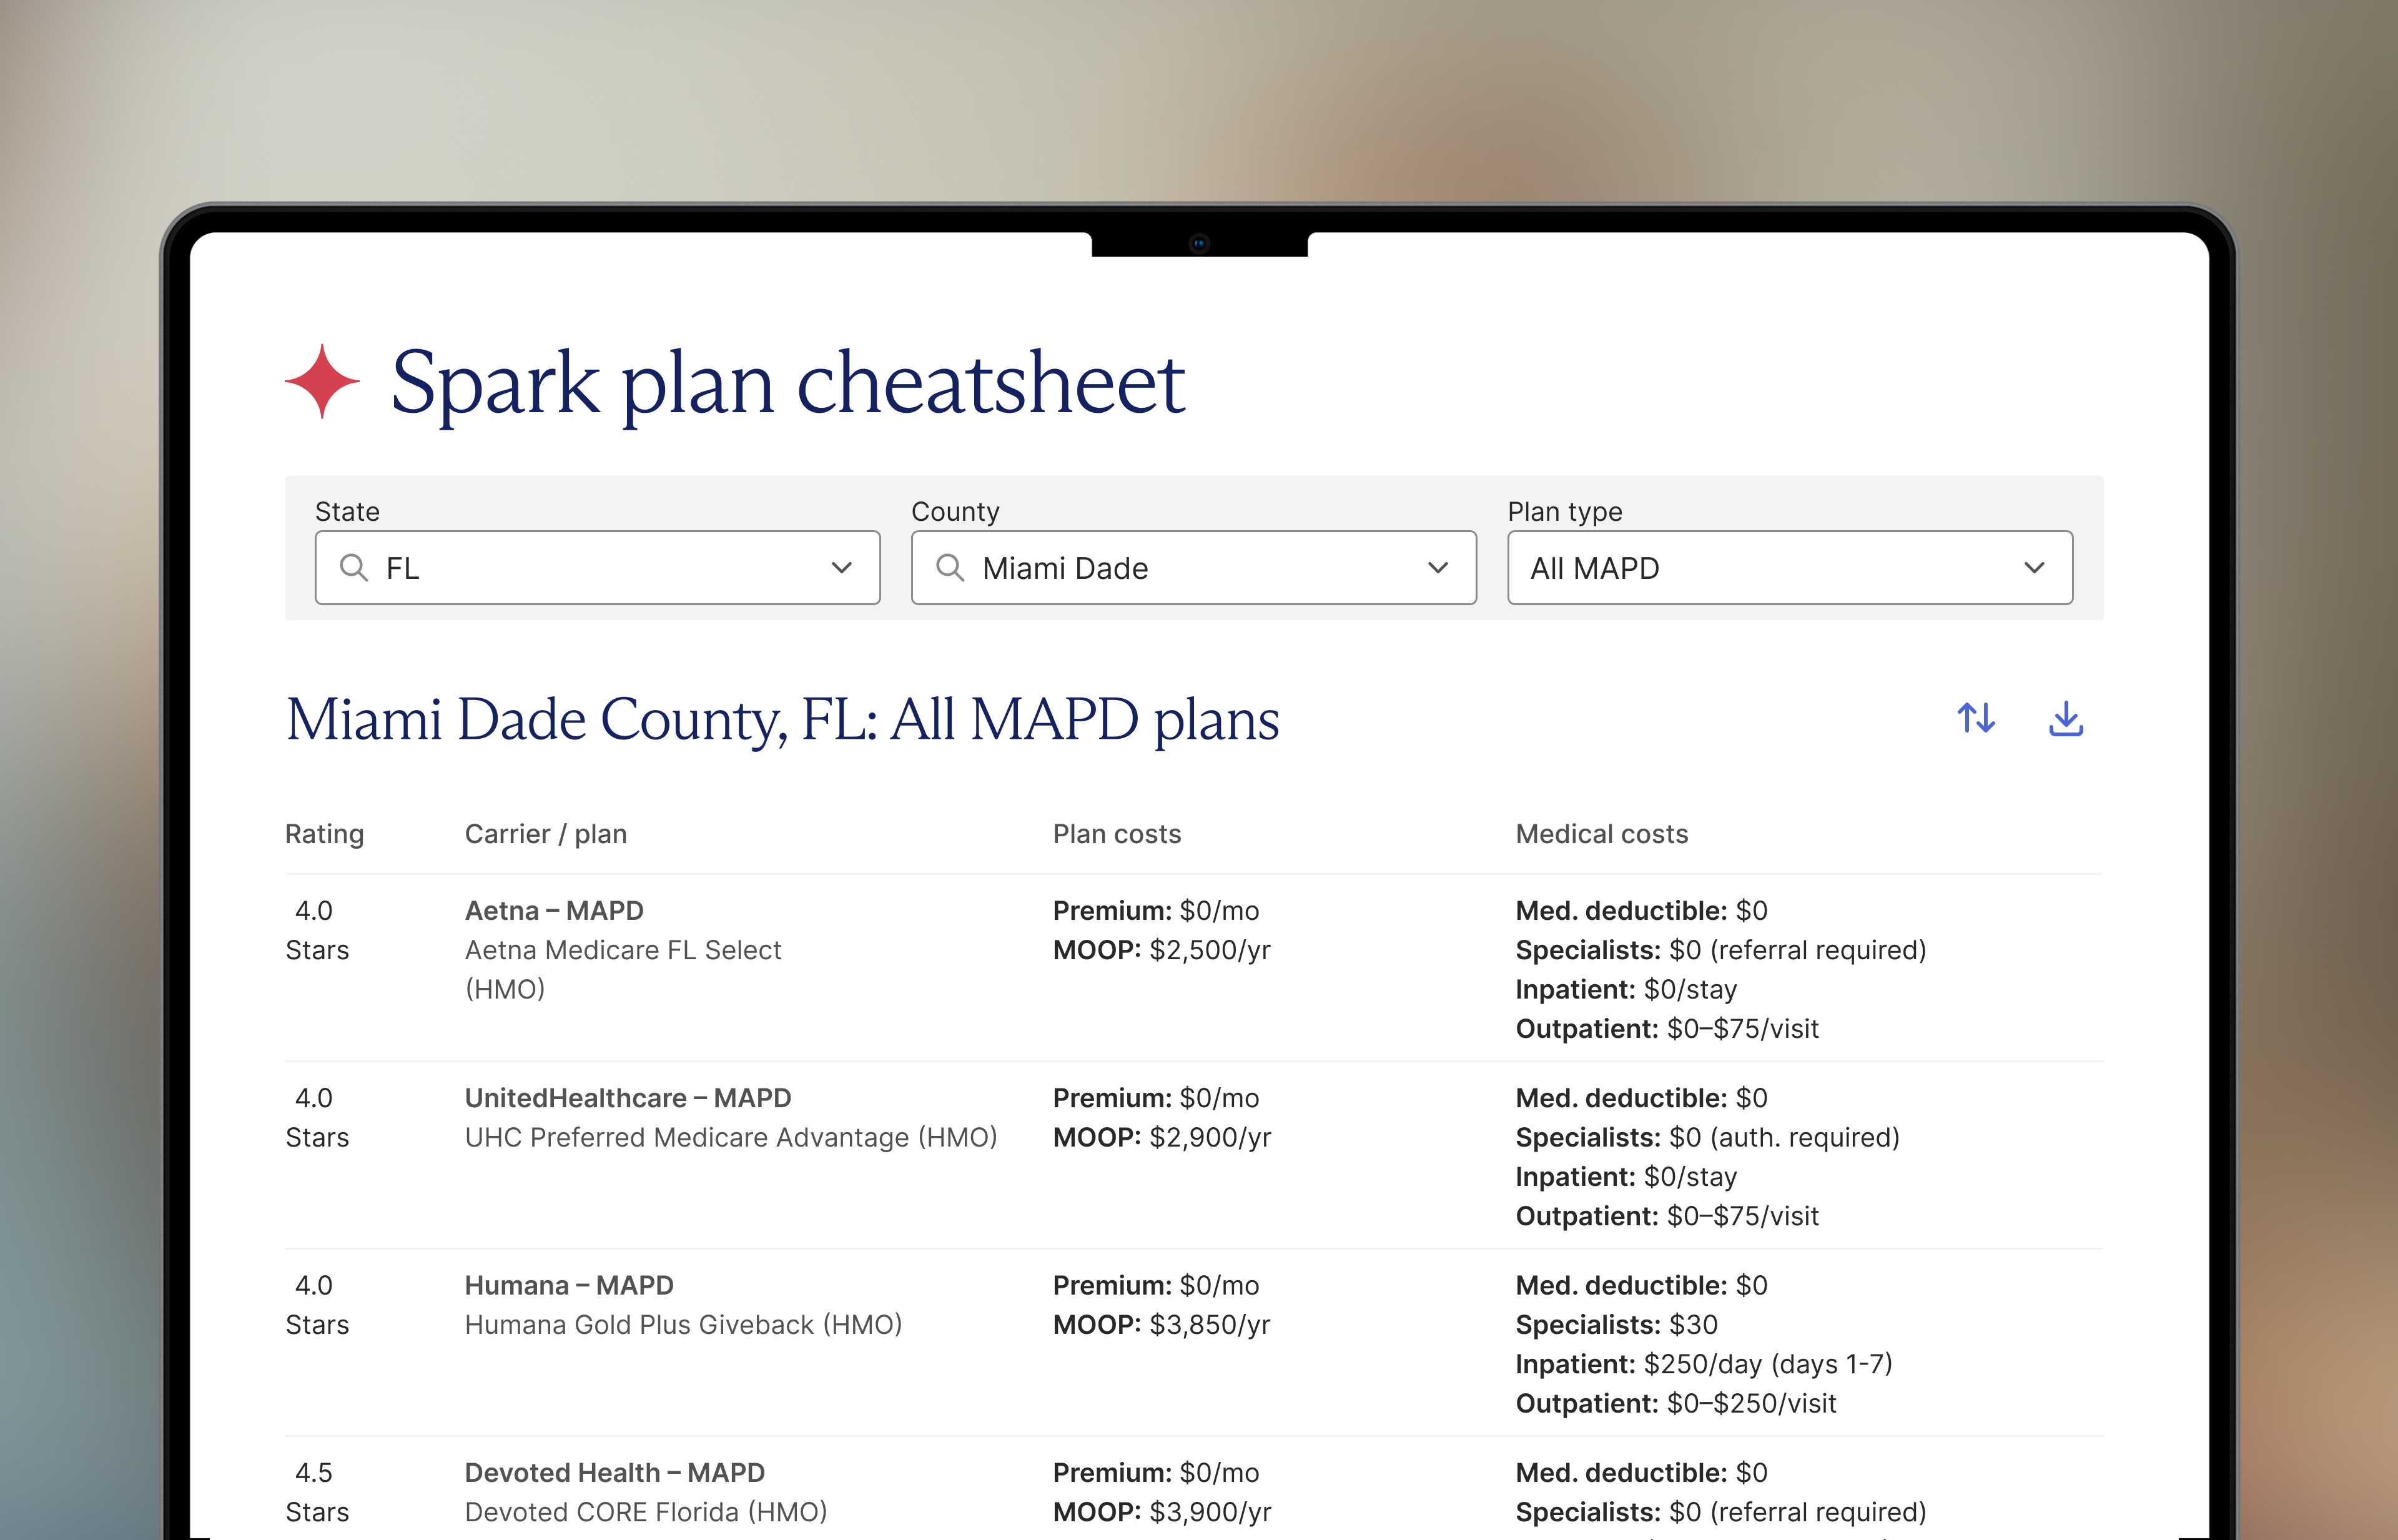
Week one: Pick one or two carriers to start with in Spark.
Week two: Build scripting for cross-selling and bundling conversations.
Week three: Go through your book and pick ten clients you're genuinely glad to talk to.
Week four: Start outreach and practice introducing the new products.
Give clients credit, and move first
Affordability shouldn't be the default assumption. The better approach: talk to people with the assumption that they're smart and capable of making informed decisions, not the assumption that they can't afford more coverage.
There's also a competitive angle worth remembering. If an agent isn't selling life insurance to their clients, somewhere a life insurance agent is getting AHIP certified right now, and they're going to try to talk to those same clients.
Have the conversation, whatever it is. The agents who build lasting income aren't the ones with the biggest single book of MA clients. They're the ones who diversify, bundle, and show up as a full retirement benefits advisor instead of a single-product agent.